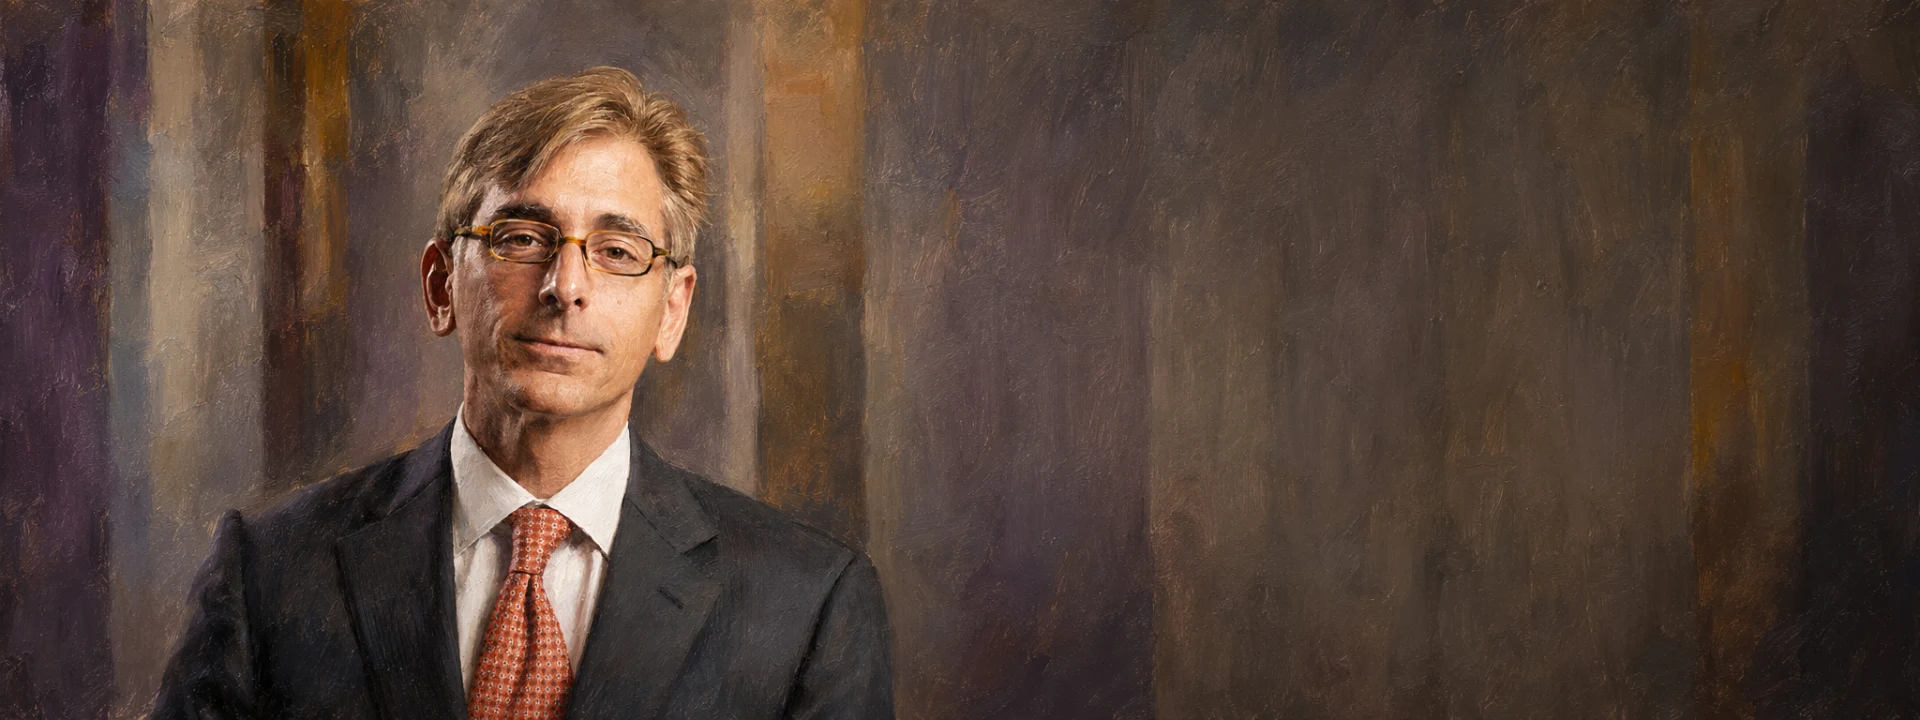
Salvatore J. Graziano
Securities Fraud · Pharmaceutical Science · Trial Preparation · Investor Rights
I love the challenge of proving our cases.
Weeks Before Trial
Salvatore J. Graziano prosecuted crimes in Manhattan before he began proving securities fraud for pension funds. Twice he took a pharmaceutical company to the eve of a jury trial in Newark, and the two settlements, $688 million and $1.062 billion, remain the largest a drug maker has paid to a shareholder class.
When Salvatore J. Graziano stood up in a Manhattan courtroom as an Assistant District Attorney, the room was usually with him. “As a prosecutor, I’d walk into court and, most of the time, the judge was already on my side, the jury was on my side,” he said in 2025, and so were the court officers. Then he moved to private practice and began suing companies on behalf of the investors they had misled. “So now I’m in this new field—I’m a private securities litigation attorney, and everything is the opposite.” He has spent three decades in that field, the last twenty years of it as a partner at Bernstein Litowitz Berger & Grossmann, where he sits on the Executive Committee and leads cases for public pension funds and other institutional investors. He was introduced to plaintiff-side securities law in 1995, and “after that, defending big corporations seemed wrong.”
The measure of the change is two cases against pharmaceutical companies that he carried to the courthouse door. In the Schering-Plough ENHANCE action, with trial set for March 4, 2013 before Judge Dennis M. Cavanaugh in Newark, Schering, Merck and the underwriters paid $688 million a few weeks before trial was to begin. In the Merck Vioxx action, with trial set for March 1, 2016, also in Newark, and his team’s hotel rooms near the courthouse already reserved, Merck agreed to $1.062 billion, the largest securities fraud class action settlement ever obtained from a pharmaceutical company and the second largest in the Third Circuit. Around them came $300 million from General Motors, $480 million from Wells Fargo, $450 million from Kraft Heinz, $234.3 million from the remains of MF Global, and a unanimous Supreme Court ruling, Merck & Co. v. Reynolds, on when the clock starts running on a securities fraud claim. “I love the challenge of proving our cases. It is very difficult,” he said in 2018. “Unless you bring yourself to the expert level of your adversary, you will not be successful.”
A Crash Course on Litigation
He is a lifelong New Yorker, raised by immigrant parents, and he did not speak English until he entered the city’s public schools: “I did not learn to speak English until attending public school in New York City.” He lives near a federal courthouse in Manhattan and sees the people lining up for naturalization hearings, as his parents once did; he can point them to the right building before they finish asking where it is, and he hopes their children will have the opportunities he had. He took his psychology degree cum laude from New York University in 1988 and his law degree, also cum laude, from New York University School of Law in 1991. An intensive criminal-law clinic in his third year—“a crash course on litigation that cannot be replicated any place else,” he has called it—led him to the Manhattan District Attorney’s Office. “My public path emerged as a result of an intensive third-year law school clinic where I practiced criminal law,” he said; the clinic taught him what judges need to know and what jurors expect at trial. He served there as an Assistant District Attorney and was admitted to the New York bar in 1992.
He was introduced to plaintiff-side securities law in 1995, the year Congress passed the Private Securities Litigation Reform Act, and spent ten years in private practice prosecuting securities fraud cases before Bernstein Litowitz brought him in as a partner in its New York office on May 15, 2006. The statute changed who his clients were. “Suddenly there were very large institutional investors who stepped up to be lead plaintiffs,” he said. “They were committed to the cases, they were committed to the results.” “It was just so much better to go to court and represent, for example, the largest investor in the state of New York.” “I joined Bernstein Litowitz in 2006 because I considered the firm the best of the bar,” he said twelve years later, and his view had not changed: “Our senior founding partner Max Berger sets the tone with his unparalleled commitment to excellence and integrity.” He found the work “satisfying to hold wrongdoers accountable while facing well-credentialed and well-funded lawyers.” “In hindsight,” he said, “I couldn’t conceive a better fit.” In 2015 he put the rule he works by in two sentences: “success comes from avoiding exaggerations or speculation,” and the firm’s practice is “to be incredibly careful with our allegations. We have to make sure we are firmly convinced of them personally before we bring them in court.”
Storm Warnings
Merck began selling Vioxx in May 1999. Its VIGOR study enrolled 8,076 rheumatoid arthritis patients and compared the drug with naproxen; when the results were unblinded on March 9, 2000 they showed five times as many heart attacks in the Vioxx group, and from March 27, 2000 Merck publicly advanced what became known as the naproxen hypothesis, that naproxen had protected the heart rather than Vioxx harming it. The investors later alleged that Merck could not find evidence to support it. On September 21, 2001 the Food and Drug Administration sent a warning letter calling the drug’s marketing “false, lacking in fair balance, or otherwise misleading,” while describing the naproxen hypothesis as a “possible explanation.” On September 17, 2004 the safety monitoring board of a second study, APPROVe, unanimously recommended unblinding and stopping it. Dr. Edward Scolnick, the president of Merck Research Laboratories, reacted first that Vioxx had elevated the rate of cardiovascular events, and Dr. Alise Reicin, the executive director of clinical research, testified that her “first impression was that what we saw was a result of Vioxx and not naproxen acting as a cardioprotective agent.” Merck withdrew Vioxx worldwide on September 30, 2004, and its market capitalization fell by tens of billions of dollars. The first shareholder complaint was filed by Frank Pringle on November 6, 2003 in the Eastern District of Louisiana; the investors’ suits over what the company had said about the drug’s cardiovascular risk were sent to the District of New Jersey on February 23, 2005, before Judge Stanley R. Chesler, against Merck, Scolnick and Reicin. The Public Employees’ Retirement System of Mississippi, Steven LeVan, Jerome Haber and Richard Reynolds were appointed lead plaintiffs on January 25, 2007, when Bernstein Litowitz was added as co-lead counsel, and Graziano, who joined the case that year, led the firm’s team through the decade that followed with Katherine M. Sinderson and Adam H. Wierzbowski.
On April 12, 2007 the complaint was dismissed as time-barred. Judge Chesler held that the investors had been on inquiry notice by November 6, 2001, more than two years before the first complaint, because the “storm warnings” of October 2001, the FDA letter, the journal articles and the first product-liability suits, should have sent them to investigate. The firm argued the appeal: John P. Coffey of Bernstein Litowitz stood up on June 24, 2008 against Evan R. Chesler of Cravath, Swaine & Moore, and on September 9, 2008 the Third Circuit reversed, two to one, in an opinion by Judge Sloviter. In October 2001, the court found, analysts, scientists, the press and the FDA had all treated Merck’s explanation for the heart attacks as plausible, and “none suggested that Merck believed otherwise.” Merck petitioned for certiorari on January 15, 2009, the Supreme Court granted review on May 26, 2009, and David C. Frederick argued for the investors on November 30, 2009, with Kannon K. Shanmugam for Merck and Deputy Solicitor General Malcolm L. Stewart for the United States in support of the investors. Shanmugam warned the justices about “the ostrich plaintiff who simply lies in wait and waits to see how a company’s stock performs.” Chief Justice Roberts answered one exchange with “So inquiry notice has nothing to do with anything,” and Justice Breyer, imagining a witness in jail in Burma for three years, said that under Merck’s rule a plaintiff “would have to file a complaint possibly before he has enough evidence to even bring a case.” On April 27, 2010, in Merck & Co. v. Reynolds, 559 U.S. 633, a unanimous Court held that the two-year limitations period runs from the time a reasonably diligent plaintiff would have discovered the facts constituting the violation, including the facts showing the defendant’s state of mind, and that suspicion sufficient to prompt an inquiry does not by itself start the clock. Justice Breyer wrote that “facts showing scienter are among those that ‘constitut[e] the violation,’” and that “the ‘discovery’ of facts that put a plaintiff on ‘inquiry notice’ does not automatically begin the running of the limitations period.” Before November 6, 2001 the investors had not discovered, and Merck had not shown that a diligent plaintiff would have discovered, “the facts constituting the violation.” Justice Scalia, joined by Justice Thomas, would have gone further: “actual discovery is what § 1658(b)(1) requires to start the limitations period.”
Fifty-Nine Depositions
Merck moved to dismiss again in June 2010. After argument on July 12, 2011, the court sustained the claims on August 8, 2011 in all material respects, finding false statements and scienter adequately pleaded against the company and its two top scientists, and on January 30, 2013 it certified a class of investors from May 21, 1999 through September 29, 2004, found each of the four lead plaintiffs adequate and appointed the firm class counsel. Discovery ran to fifty-nine depositions, fourteen of them of experts, more than sixty third-party subpoenas and more than thirty-five million pages from Merck and third parties, 35.8 million of them reviewed by the investors’ lawyers; the investors’ experts covered biostatistics, cardiology, the regulation of the drug, gastroenterology and damages, among them Tabak on market efficiency and damages, Zipes on cardiology, Madigan and Woodward on statistics and epidemiology, Kessler on FDA regulation and Boghigian on pharmaceutical marketing. Summary judgment motions were filed on January 17, 2014. On May 13, 2015 Judge Chesler largely denied Merck’s motions for summary judgment, finding evidence from which a jury could conclude that the defendants had knowingly or recklessly misled investors about the cardiovascular-safety studies and data, and set trial for March 1, 2016. The parties briefed their motions to limit expert testimony in August and September 2015, completed a joint pretrial order, and the investors’ lawyers ran a multi-day mock trial. The problem, Graziano said afterward, was less the cardiology than the jury: “We had years to learn this material, but how do you communicate it in a way that [the jury] would understand?”
The court-appointed mediator, Layn R. Phillips, a former federal judge, had held settlement conferences with the parties over several years. On December 17, 2015, after both sides accepted his proposal, they reached an agreement in principle, and Merck announced it on January 15, 2016: $830 million plus court-approved fees and expenses, about $680 million after insurance, charged to the fourth quarter of 2015, with no admission of liability by the company, Scolnick or Reicin. The announcement surprised Graziano. His team had reserved hotel rooms near the courthouse for a trial weeks away. “We had all the logistics worked out.” The stipulation was signed on February 8, 2016: $830 million into a fund for the class and $232 million into a separate fund for fees and expenses, any part of it not awarded going to the class, with counsel permitted to seek up to 20 percent in fees and up to $19 million in expenses. The notice to the class estimated about $0.36 for each affected share of common stock, and the combined $1.062 billion ranked among the fifteen largest securities class action settlements since the PSLRA, the largest ever obtained from a pharmaceutical company and the second largest within the Third Circuit. Graziano signed the settlement papers as co-lead counsel with Robert A. Wallner of Milberg, David A.P. Brower of Brower Piven and Mark Levine of Stull, Stull & Brody. Judge Chesler heard the motion at 10 a.m. on June 28, 2016 in Courtroom 2 in Newark and gave final approval that day; he approved the distribution plan on September 13, 2018, and the net fund has been paid out in full. The length of the case and the Supreme Court victory, Graziano said, put it “into the firm’s proudest legacy of success.”
March 4, 2013
Vytorin combined Schering-Plough’s Zetia with generic simvastatin, and the ENHANCE study, completed in April 2006, compared the combination with simvastatin alone and found no statistically significant difference in its measure of atherosclerosis. For two years the company marketed Vytorin and Zetia without disclosing the result. In November 2007, eighteen months after the study closed, the company announced a change to its primary endpoint, later withdrew the change, and still released no results, while Congress and federal and state prosecutors demanded the study data; Merck partially released the results on January 14, 2008, reporting “no statistically significant difference” in plaque buildup, and the House Energy and Commerce Committee opened an inquiry. The complete results came out on March 30, 2008 at the American College of Cardiology meeting in Chicago, where a panel of cardiologists recommended the two drugs only after other treatments had failed, and Schering’s stock fell that day by about 26 percent, erasing roughly $8.2 billion. In the District of New Jersey, Judge Dennis M. Cavanaugh appointed the Arkansas Teacher Retirement System, the Public Employees’ Retirement System of Mississippi, the Louisiana Municipal Police Employees’ Retirement System and the Massachusetts Pension Reserves Investment Management Board lead plaintiffs on April 17, 2008, with Bernstein Litowitz and Labaton Sucharow as lead counsel; Graziano led the firm’s team with Gerald H. Silk and Adam H. Wierzbowski for the class that bought between January 3, 2007 and March 28, 2008. The defendants were Schering, the Merck/Schering-Plough joint venture, their officers and directors, and the underwriters of Schering’s common stock offering of August 9, 2007 and its 6 percent mandatory convertible preferred offering of August 15, 2007. The motions to dismiss were denied in full on September 2, 2009, and reconsideration was denied on June 21, 2010.
Discovery ran in the United States and abroad: more than ninety depositions, twelve million pages of documents and twenty-four expert reports. Graziano deposed the scientists who had overseen the ENHANCE trial himself, a step that risked handing the defense favorable testimony. On September 25, 2012 the court certified the class and denied summary judgment to Schering, the joint venture, the individual defendants and the underwriters. Judge Cavanaugh wrote that “the Court has no doubt that Schering stock traded on an efficient market,” rejected the argument that index and basket purchasers had not relied on the misstatements because “index purchases rely exclusively upon the market to impound any representations,” called the attack on the Arkansas fund’s Securities Act standing “devoid of merit,” and found “a causal relationship between the announcement of unexpected news and an immediate response in the price.” The Third Circuit declined to hear an interlocutory appeal of the certification. Trial was set for March 4, 2013, and notice of the pending class action went out on January 17, 2013. “We did many mock trials in preparation for the actual trial,” Laura Posner, who worked on the case, recalled. “I learned a lot watching [Graziano] explain complex ideas about securities and pharmaceuticals to jurors.” His own account: “We’re talking about Merck and Schering here. These are very large and serious companies that employ experts every day. We were litigating in their backyard, they offered a very strong defense and didn’t acknowledge any wrongdoing whatsoever.”
Before that date Schering, Merck, their officers and directors and the underwriters of Schering’s August 2007 offerings agreed to pay $473 million, and the companion Merck Vytorin/Zetia action, brought for the Jacksonville Police and Fire Pension Fund and the General Retirement System of the City of Detroit and led for the firm by Graziano and Wierzbowski, settled for $215 million; the $688 million was announced on February 14, 2013. Merck, which had absorbed Schering in November 2009, said both companies had acted responsibly in connection with the trial and admitted nothing, and recorded a $493 million after-tax charge that cut its reported fourth-quarter 2012 profit from 46 cents a share to 30. The combined figure was then the largest securities class action recovery from a pharmaceutical company, a mark his own Vioxx settlement passed three years later, and it stood second among all securities class settlements in the Third Circuit and among the ten largest in a case without an accounting restatement. Judge Cavanaugh approved both settlements on October 1, 2013, after more than 346,000 notice packets had gone to the Schering class and 725,000 to the Merck class, finding each “fair, adequate, and reasonable in light of the Girsh factors,” with one opposition in each action and settlements reached “only a few weeks before trial was to begin.” The Special Masters, Stephen M. Greenberg and Jonathan J. Lerner, called the result “extremely impressive,” and said of the Merck action that it was so “given the particular challenges presented by the Merck Action in proving causation”; the court awarded fees of 16.92 percent of the Schering fund and 28 percent of the Merck fund on their recommendation. A cy pres distribution of the remainder was approved on January 24, 2019, and both funds have been paid out.
Seven Hundred Seventy-Nine Thousand Cars
On February 13, 2014, General Motors recalled 779,000 Chevrolet Cobalts and Pontiac G5s for defective ignition switches and disclosed twenty-two crashes in which the airbags had not deployed, six deaths among them; on February 25 it recalled 842,000 more cars, more than 1.6 million worldwide between the two recalls, and corrected the count to thirty-one accidents and thirteen deaths. On March 11, 2014 the Justice Department, the United States Attorney in Manhattan and the Senate Commerce Committee announced investigations, the House Energy and Commerce Committee demanded documents from the chief executive, Mary Barra, and the stock fell from $37.09 to $35.18, its largest one-day drop in more than two years, about $2.4 billion of market value. The New York State Teachers’ Retirement System, which put its own loss at more than $6 million, sued in the Eastern District of Michigan over the company’s statements that its cars were vigorously tested before being offered to customers and over its accounting for warranty and recall liabilities, and Judge Linda V. Parker appointed it lead plaintiff on October 24, 2014; Graziano led the firm’s team with Silk, James A. Harrod, Wierzbowski and Rebecca E. Boon. Their investigation reached former GM employees, among them a thirty-year veteran who had headed the company’s corporate quality audit and sat for multiple interviews, the consumer complaints that the House committee had made public, the record of the National Highway Traffic Safety Administration as a regulator, and the Valukas report on the recalls delivered to GM’s board on May 29, 2014; the lawyers reviewed and coded more than four million pages. The case, Graziano said, was the “polar opposite” of Merck. It had to be built from the personal-injury trials, the news coverage, the changes in GM’s leadership and decades of the company’s dealings with regulators, and the central difficulty was “toeing the line between advancing shareholders’ claims and being respectful of these tragic events,” a defect across twenty GM models that killed at least 124 people.
The consolidated complaint was filed on January 15, 2015, GM moved to dismiss on March 13, and the briefing closed on July 10. The parties had chosen a mediator and set a session for October 21, 2015, with opening briefs due September 23, but direct talks between counsel overtook the schedule, and while GM’s motion was awaiting decision they agreed, on September 16, 2015, on a $300 million settlement. GM had argued that nothing in its statements was false, that the lead plaintiff had pleaded no facts showing otherwise, and that the stock declines had not been caused by any revelation of the truth; against a damages range that ran from $1.2 billion to $2.8 billion depending on how loss causation came out, the cash represented between 11 and 25 percent of the possible maximum, which Graziano told the court was the second largest securities class recovery within the Sixth Circuit. Judge Parker gave preliminary approval on November 20, 2015. By March 8, 2016, 1,181,701 notice packets had gone out, drawing forty-three requests for exclusion, one generalized objection and no objection to the plan of allocation; the lawyers reported 25,527.70 hours of work and asked for 7 percent of the fund, $21 million, about 1.9 times their lodestar of $10,873,042. Judge Parker gave final approval on May 19, 2016, entering judgment on May 23; the Sixth Circuit rejected a class member’s pro se appeal on November 27, 2017, the Supreme Court declined review on October 29, 2018, and the fund was distributed beginning July 31, 2019, with further rounds in October 2021 and October 2024.
Two Weeks in September 2016
On September 8, 2016, regulators disclosed that Wells Fargo employees had opened millions of accounts their customers had not authorized, as many as 2.1 million deposit and credit card accounts by the first count and about 3.5 million by the bank’s own later acknowledgment, to meet the sales targets of the cross-selling model the bank had praised to investors; regulators fined the bank $185 million, and over the following two weeks the disclosures continued, and the chief executive, John Stumpf, testified before Congress that senior executives and the board had known of the practice on a significant scale by 2013. The first securities suit was filed in the Northern District of California on September 26, 2016. Union Asset Management Holding AG sued for investors who had bought the stock between February 26, 2014 and September 20, 2016, under Sections 10(b), 20A and 20(a) of the Exchange Act, and Judge Jon S. Tigar appointed it lead plaintiff on January 5, 2017 and the firm lead counsel on May 27, 2017; Graziano led the team with Wierzbowski, Boon and Scott R. Foglietta. On February 27, 2018 Judge Tigar largely denied the motions to dismiss, sustaining most of the claims against the bank and its executives, and the investors filed a second consolidated complaint on March 15.
On May 4, 2018 the parties announced a $480 million cash settlement, the fourth largest securities settlement ever reached in the Ninth Circuit when it was announced; the bank denied the allegations. The stipulation was filed on July 30, preliminary approval granted on September 4, and on December 18, 2018, on Graziano’s declaration of November 13, Judge Tigar approved the settlement and the plan of allocation, entering judgment two days later. He awarded counsel $95.9 million in fees, 20 percent of the fund, and wrote that “Plaintiffs’ counsel obtained an excellent result for the class when compared to similar cases, despite comparable risks”; 253 investors excluded themselves, the judgment recorded no objection, and the Ninth Circuit affirmed the fee award on April 20, 2020. The bank’s spokesman, Peter Gilchrist, said “We are pleased to put this matter behind us,” and the bank admitted and denied nothing. Graziano called the recovery “especially significant, because it represented a very high percentage of potential damages,” since had Wells Fargo prevailed on loss causation and damages, “$480 million could have exceeded the figure recoverable at trial”; “We’re particularly proud of what we’ve achieved in that case.” The class has been paid in four distributions, in September 2020, August 2021, September 2022 and August 2024, about $0.35 a share after fees, with more to follow while the remaining funds justify them.
$15.4 Billion
Kraft Foods Group and H.J. Heinz merged in 2015 under 3G Capital, which sold $1.2 billion of Kraft Heinz stock over the next four years, and on February 21, 2019 Kraft Heinz wrote down the Kraft and Oscar Mayer brands by $15.4 billion, one of the largest goodwill impairments since the financial crisis, cut its dividend by 36 percent, reported a $12.6 billion loss for the fourth quarter of 2018, and disclosed a Securities and Exchange Commission subpoena and an internal investigation into side agreements with vendors, which cost a further $25 million charge and, later, a $62 million settlement with the Commission. Sjunde AP-Fonden and Union Asset Management, appointed lead plaintiffs in the Northern District of Illinois on October 8, 2019 for the class that bought between November 6, 2015 and August 7, 2019, alleged that undisclosed cuts to the business had been eroding the brands while the company described the savings as sustainable: 3G’s across-the-board cuts, they said, had gutted research, quality control and the supply chain. Bernstein Litowitz and Kessler Topaz Meltzer & Check were lead counsel, and Graziano led the firm’s team with Katherine M. Sinderson and Erika Connolly against Kraft Heinz, 3G, Bernardo Hees, Paulo Basilio, David A. Knopf, Alexandre Behring, George Zoghbi and Rafael Oliveira. The investigation behind the pleading ran to more than 320 witness interviews and about 1,390 leads, and the complaint rested on the first-hand accounts of twenty-six former employees and contractors. After the plaintiffs amended the complaint on August 14, 2020 with new information about internal projections of earnings that had surfaced in the Delaware derivative case, Judge Robert M. Dow Jr. sustained it over renewed motions to dismiss on August 11, 2021, denying them in their entirety: the plaintiffs, he wrote, “point to several allegations that, considered together, raise a cogent and compelling inference of scienter,” they “need not point to a single revelation that exposes the entirety of the alleged fraud,” and “the whole point of the merger was to put 3G’s partners in control of Kraft Heinz.”
The defendants and third parties produced more than 14.7 million pages; the plaintiffs served document subpoenas on twenty-three third parties, among them five former directors including the 3G co-founders Telles and Lemann, obtained letters rogatory in Canada and more than 179,000 pages from nonparties, agreed to 240 hours of merits depositions, and moved for class certification on March 28, 2022, a motion still pending when the case settled. The defendants had argued that the risks were disclosed and known to the market, that the procurement fraud was immaterial, and that commodity inflation, foreign exchange and the costs of international transactions explained the losses, and the defendants owned or controlled half of the company’s equity. Two mediation sessions before Layn Phillips, on January 31 and February 3, 2023, produced a mediator’s recommendation on February 7 that the parties accepted on February 13; the term sheet of March 14 set $450 million in cash, paid by the defendants and their insurers, which Phillips called “a recovery and outcome that is reasonable and fair for the Settlement Class and all Parties involved.” Graziano and Sharan Nirmul of Kessler Topaz told the court that the sum was roughly 8.7 percent of the maximum damages of about $5.2 billion and between 10.4 and 14 percent of the more realistic range, and the largest pre-trial securities class action settlement in the Seventh Circuit. After 1,653,764 postcard notices went out, no class member objected to the settlement or the plan of allocation, and Judge Jorge L. Alonso, finding no objection from any class member, approved the settlement, found it negotiated at arm’s length and “in all respects, fair, reasonable, and adequate to the Settlement Class,” and entered judgment on September 12, 2023, awarding fees of 20 percent and $2,656,091.93 in expenses a week later. The first distribution went out in May 2025 and the second in April 2026.
Five Settlements
MF Global reported a net loss of $191.6 million for the quarter ended September 30, 2011 on October 25 of that year, and its stock fell about 48 percent; the New York Stock Exchange halted trading on October 28, and the firm filed for Chapter 11 on October 31. The investors, led by the Virginia Retirement System and the province of Alberta, alleged that the company’s financial statements had not complied with GAAP, that its filings had hidden the risk of the $6.3 billion bet on European sovereign debt that its chief executive, Jon Corzine, had made through repurchase-to-maturity transactions, and that the firm had violated its own controls, misappropriating about $1.6 billion from segregated customer accounts. Judge Victor Marrero appointed Virginia co-lead plaintiff and Bernstein Litowitz co-lead counsel on January 20, 2012, and Graziano led the firm’s team with Hannah Ross, alongside Javier Bleichmar of Bleichmar Fonti Tountas & Auld. A global mediation before Judge Daniel Weinstein in 2013 failed; on November 12, 2013 the court denied the motions to dismiss, and discovery began that December. PricewaterhouseCoopers produced more than 213,000 documents by subpoena before the investors added it as a defendant on October 3, 2014, and by May 2015 the lawyers had taken or defended about thirty depositions, among them three days of testimony from Corzine. There was no government case to lean on. “It was an uphill battle in the sense that we believed in the allegations but we needed to prove them,” Graziano said. “We didn’t have any kind of help from outsiders.” The action was resolved through five settlements totaling $234.3 million: $74 million from certain underwriters, approved June 26, 2015; $932,828 from Commerz Markets; $65 million from PricewaterhouseCoopers, reached on February 25, 2015 at a mediation before Layn Phillips; $64.5 million from Corzine, the former chief financial officers J. Randy MacDonald and Henri Steenkamp and seven former independent directors, paid by their insurers, reached on May 8, 2015 before Magistrate Judge James C. Francis and approved November 25, 2015; and $29,825,000 from the remaining senior-notes underwriters, approved July 15, 2016. The distribution plan was approved on October 30, 2018 and the fund has been paid out.
In the spring of 2012 the chief executive of JPMorgan Chase, James Dimon, called reports of enormous credit-derivative positions in the bank’s Chief Investment Office a “complete tempest in a teapot”; on May 10, 2012 he said he had been “dead wrong” and announced losses of about $2 billion, which grew to more than $5 billion, and the shares fell nearly 10 percent, about $15 billion in a day. The Arkansas Teacher Retirement System and the Oregon State Treasurer, with the Oregon Public Employee Retirement Board, sued in the Southern District of New York over the bank’s description of the office as a hedging unit and its reported value at risk; Judge George B. Daniels appointed them lead plaintiffs with Bernstein Litowitz as co-lead counsel on August 21, 2012, and Graziano was among the partners who led the case with Avi Josefson, John Rizio-Hamilton, Jonathan D. Uslaner and Michael D. Blatchley. On December 18, 2015 the bank agreed to pay $150 million in cash, and Judge Daniels approved the settlement on May 10, 2016. In the same years Graziano, Rizio-Hamilton and Wierzbowski led the firm’s side of the Facebook IPO litigation before Judge Robert W. Sweet, for the North Carolina Department of State Treasurer, the Arkansas Teacher Retirement System, the Fresno County Employees’ Retirement Association and Banyan Capital, over the May 2012 offering of 421 million shares at $38 that raised more than $16 billion while analysts’ cuts to the company’s estimates reached only select clients; days after the offering Graziano said on Reuters TV that “the plaintiffs do have a pretty good leg to stand on here.” The motion to dismiss was denied in December 2013, the class certified in December 2015, and with trial set for February 2018 Facebook agreed in December 2017 to pay $35 million, approved in November 2018 and affirmed by the Second Circuit in September 2020. With Sinderson he led the SunEdison case for the Municipal Employees’ Retirement System of Michigan after the solar company reclassified about $740 million of debt from non-recourse to recourse in November 2015, having borrowed $170 million from Goldman Sachs for a year at an effective 15 percent, and then filed for bankruptcy in April 2016 with its stock down more than 95 percent; “a tough fight,” he called it in 2018, with class certification briefed and depositions running into the fall. Judge P. Kevin Castel certified the class on January 7, 2019, the parties agreed in June 2019 on $74 million plus a contingent payment of up to $2 million, and the court approved the settlement on October 25, 2019.
Two Writs
Two securities cases in which Graziano appeared for the investors reached the Supreme Court in the October 2024 term. The Facebook case was brought by the Public Employees’ Retirement System of Mississippi and its co-lead plaintiffs, who alleged that the company’s risk disclosures described the misuse of user data as a hypothetical after Cambridge Analytica had already obtained the data of tens of millions of users; Facebook had privately confirmed the harvesting within days, told the public only that it was carefully investigating, kept working with the firm on election advertising for two years, and lost $100 billion in market value within a week of the March 2018 disclosures. Its annual report had warned that “[a]ny failure to prevent or mitigate . . . improper access to or disclosure of our data or user data” could cause harm. The Ninth Circuit had held on October 18, 2023, in an opinion by Judge M. Margaret McKeown over a partial dissent by Judge Patrick J. Bumatay, that the falsity of the risk disclosures and loss causation were adequately pleaded, because the company “represented the risk of improper access to or disclosure of Facebook user data as purely hypothetical,” and Facebook asked the Court to hold that a risk disclosure can never mislead by omitting a past event. “It’s a pattern that a company purports to warn about a risk that could happen when the risk already has happened,” Graziano said of the case. E. Öhman J:or Fonder AB and Stichting Pensioenfonds PGB brought the NVIDIA case, alleging that the company had understated how much of its gaming revenue in 2017 and 2018 came from cryptocurrency miners, who bought GeForce cards by the thousands for mining farms and accounted, the complaint said, for more than 60 percent of GeForce sales, while Jensen Huang called the business small and, asked about it in November 2017, said “Maybe $70 million”; the Ninth Circuit had held on August 25, 2023, in an opinion by Judge William A. Fletcher, that the claims against the company and its chief executive were adequately pleaded, finding that “Huang’s access and review of contemporaneous reports are the most direct way to prove scienter,” and NVIDIA asked the Court to tighten the pleading standards for falsity and scienter.
Graziano signed the respondents’ briefs in both cases, filed on September 24 and 25, 2024—in Facebook with Jeremy P. Robinson of his firm, Robbins Geller Rudman & Dowd and the Supreme Court advocates Kevin K. Russell, counsel of record, and Daniel H. Woofter; in NVIDIA with John Rizio-Hamilton and Jonathan D. Uslaner of his firm, Matthew L. Mustokoff and Andrew L. Zivitz of Kessler Topaz, and Deepak Gupta of Gupta Wessler as counsel of record. The Facebook brief conceded the question as Facebook had framed it, that an immaterial past event need not be disclosed, and argued that the Ninth Circuit had never held otherwise and that whether a statement misleads depends on its facts and context; the NVIDIA brief opened with the words “Nvidia sells computer chips” and argued that the Reform Act nowhere bars allegations drawn from expert analysis. The Court heard argument on November 6 and November 13, 2024. Kannon K. Shanmugam, for Facebook, called the Ninth Circuit’s rule “an outlying rule that threatens to create a sweeping regime of securities liability for omissions,” and when he turned to materiality Justice Sotomayor cut him off: “That’s a different issue. That’s not what we granted cert on.” Justice Kagan put the case in one hypothetical, a company warning that a fire at its production plant could impair its sales after a fire had destroyed half its capacity. The Court dismissed both writs as improvidently granted—Facebook on November 22 and NVIDIA on December 11, 2024—leaving the Ninth Circuit’s judgments in place and the claims in the district courts; Graziano did not argue either case but was deeply involved in every other part of them. “It’s a bit of a cliché, but you have to love what you do,” he said after the term. “I just continue to be determined to prove the merit in our cases. Achieving that success is very rewarding.” There the cases have moved: the investors filed a fourth amended complaint against Facebook on July 1, 2025, which Judge Edward J. Davila sustained in part on February 27, 2026, and on March 25, 2026 Judge Haywood S. Gilliam Jr. certified the class of NVIDIA shareholders who bought between May 10, 2017 and November 14, 2018, with Lannebo Kapitalförvaltning AB, the successor to the Öhman fund, and PGB as class representatives, holding that the investors were entitled to the presumption of reliance and that NVIDIA had failed to rebut it.
Forced Arbitration
Outside his cases he has spent twenty years arguing for the courthouse itself. On March 10, 2008 he submitted written testimony to the Securities and Exchange Commission’s Advisory Committee on Improvements to Financial Reporting, ahead of its March 13 meeting, opposing a proposed professional-judgment framework that, he wrote, “essentially will immunize issuers and auditors from meritorious regulatory oversight and civil liability.” “The goal of enforcement is to promote good faith reporting by punishing bad faith reporting,” he told the committee, and he closed on the restatement scandals of the previous decade: “This recent history offers a lesson too painful to be learned a second time.” He served as President of the National Association of Shareholder & Consumer Attorneys, led the firm’s subprime litigation group in the years after 2008, is Senior Vice President of the Institute for Law and Economic Policy, sits on the Financial Reporting and Securities Regulation Committees of the Association of the Bar of the City of New York, has repeatedly guest lectured at Columbia Law School on securities fraud litigation and shareholder rights, and co-wrote the opening chapter, “Plaintiffs’ Perspective,” of the LexisNexis treatise Litigating Securities Class Actions. He told the Advisory Committee that his views were his own, and the pattern of his public writing has been one argument: that investors must keep their access to court. In 2018 he called the bill then before Congress to roll back parts of Dodd-Frank “a solution in search of a problem,” and in a February 2019 paper with Robert Trisotto he recounted how the SEC had refused in 2012 to accelerate the registration of The Carlyle Group after it proposed to force its shareholders into arbitration, and had told Gannett that a similar proposal “would cause the company to violate the federal securities laws.” “Absent public accountability, companies can keep their misconduct a secret, hiding it from the public in perpetuity,” the paper argued; private class actions had recovered about $19.4 billion for investors in the period it examined, more than ten times what the Commission had, and “Investors should stand together against these renewed attacks on fundamental shareholder rights.”
The National Law Journal named him a Plaintiffs’ Lawyers Trailblazer in 2019, Law360 has named him an MVP five times, in 2013 for the Merck and Schering-Plough cases, in 2015 and 2016 for MF Global, General Motors and the JPMorgan recovery, and most recently in November 2025 as one of five securities lawyers chosen, and in 2025 Law360 named him a Titan of the Plaintiffs Bar for the Supreme Court work in the Macquarie, Facebook and NVIDIA cases. Andrew Zivitz of Kessler Topaz, his co-counsel in NVIDIA and Kraft Heinz, described sending the firm a lengthy filing to review in a case Kessler Topaz was leading: “Within 24 hours, Sal called me and provided what ended up being valuable feedback. He could easily have given the assignment to a younger member of his team, but he chose to do it himself.” Laura Posner, who tried the ENHANCE mock trials with him, said that “he’s very dedicated to investors’ rights and doing what is in the best interest of shareholders,” and that the two continue to work together on appellate and Supreme Court cases for the plaintiffs’ bar. He and his wife have two daughters, and the family has traveled widely; of one daughter’s solo trip to Europe as a teenager he said, “Why not, it’s just a six-hour flight.” In September 2025 the SEC reversed decades of policy and said it would permit public companies to adopt forced arbitration clauses. Graziano’s answer, in March 2026, was addressed to the companies and their insurers: directors’ and officers’ coverage “will become exorbitantly expensive,” a company could face dozens or thousands of individual arbitrations instead of one consolidated case, “The PSLRA discovery stay is not applicable in arbitration,” underwriters and auditors would likely not be bound by the clauses at all, and “It will be impossible for insurers to assess the value of potential securities claims.” “This is a mess that insurers, and the corporations they work for, should steer clear of,” he wrote, and ended with a question: “Here we go again?”